Showing posts with label izettle. Show all posts

Thursday, 28 November 2013

The importance of conversion in prepaid programmes

At Fifth Dimension we regularly talk about “conversion ratios” – almost to the point of being boring. But we think it’s for good reason, and here’s why. 


Firstly, it's hard work generating new customers in most sectors and this is especially true for prepaid card and electronic money programmes. With budgets being continually scrutinised then the level at which you can convert prospects to customers has never been more important.

So how we do measure it?

Conversion ratio % =
 number of new customers

number of website visitors

The graph below shows the number of new customers generated from 20k monthly visits, according to different on-site conversion ratios.

So a programme with 3% conversion will generate 600 new customers per month, whereas a programme with a 6% conversion will generate 1,200 new customers.
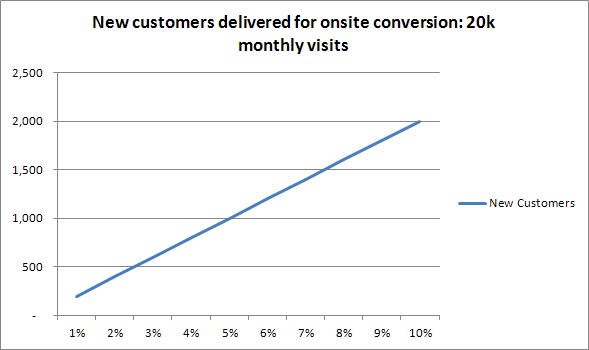


We think that’s quite a sizeable difference given what appears to be only a small change in conversion %. But to highlight this further, let’s look at the impact of not improving the performance? The chart below shows that if we wish to still deliver the 1,200 new customers per month at a conversion ratio of 3%, then a programme will also need to double its traffic to 40,000 visitors!


Regardless of how you generate it, that is a lot of new traffic to deliver and is considerably more expensive than optimising your current performance.

We think it's a no-brainer. If you do to, and would like help in measuring and improving the conversion for your current programme, then get in touch with Phil Campbell via phil@fifthdimension.com

Wednesday, 5 December 2012

Yet another Mobile POS: Adyen

It's another week, so yet another article on a Mobile POS system - this time from the gigaom.com website look at how Adyen's Shuttle compares against existing devices from iZettle and Payleven.

Adyen's mobile POS solution, Shuttle
Yet another Mobile POS: Adyen's Shuttle
The interesting point is that Adyen is not aiming at the small business and sole traders that the likes of iZettle and Payleven are targetting, but the larger business. They are also looking to white label the product which they can do due to their end-to-end payment processing, and so are not reliant on banking partners.

We've previously highlighted our concerns over the issue of consumer trust in these devices. But that can be alleviated through greater exposure and resultant familiarity to the product, coupled with a brand that they trust. Being able to deliver larger volumes of units will help with the former, and white labelling the latter.

But if there's one thing we can be certain of...the space around Mobile POS is only going to get more crowded, not less.

Read the full article on the gigaom website

Friday, 16 November 2012

Card payments on your mobile - no hardware required

Mobile payments company Flint, has recently come to the end of its Beta. If you don't know who Flint are, but are weary with hearing of yet another "mobile payments" company, then think again ...Flint have a twist on the landscape as they read the card numbers of the payment card via the mobiles camera phone. No additional hardware needed!


Mobile Payments company Flint
Flint can take card payments on your mobile, without
the need for any additional hardware

 Given the fiddliness of carrying around a dongle as per the solutions from Square, iZettle, MPowa, Payleven (shall we go on...) then Flint really have a point of difference.

Yet, we still can't help raising the concern that more than the other solutions, this is going to face a huge amount of consumer trust issues - how keen will the average cardholder be on having his credit, debit, prepaid card being photographed by a stranger?

We said it before, but the technology may not be the barrier here. A great idea, but we'll be watching to see how and if it can take off.

Saturday, 6 October 2012

Payleven announce chip & PIN solution for mobile payments

This week we saw mobile Payleven announce the launch of their chip & PIN solution for mobile payment acceptance. If the number of market entrants is any indication, then mobile point of sale (POS) is clearly a growing area, but it is unlikely to take off without chip & PIN: currently VISA is not preparing to accept mobile payments without chip & pin, so any entrant to the market that can only accept MasterCard really has their work cut out.

Payleven launch chip & PIN for mobile payments
Payleven's mobile payment acceptance
With a crowded space, then all the players are trying to establish their position in the market – Payleven’s release announcing them as the “first pan-European mobile payments company with Chip & PIN”.  But the detail of the release indicates they will only be accepting registrations from 15th October – so not much difference to mPowa?

We’re still interested to see how consumers will respond to mobile POS – in our own trials, less than 10% were willing to entertain using their card to make a payment through a mobile phone. While Chip & PIN is intended to offer greater security around the payment process, we must consider that the consumer may be even more reluctant to enter their PIN in a mobile device.

For the market to fulfil the potential expected by the mobile payment  providers, then the issue may not be one of technology solutions, but of establishing consumer confidence in the technology.

Saturday, 25 August 2012

SumUp joins European Mobile POS market

This week we see another entrant to the Mobile POS market in the form of SumUp - basically an opportunity for small (or simply mobile) businesses to accept card payments via a smart phone app with a plug-in card reader.

SumUp card reader and smartphone
SumUp users a plug-in card reader
and ios / Android app to take card
payments via mobile phone


SumUp are not new in this area, with the likes of Square, PayPal’s Here, iZettle, mPowa, Payleven and Intuit’s GoPayment and you can expect there to be others on the way - we know of a number under development for launch soon in the UK.

The principle is sound for a number of reasons, not least because it makes it easy for small merchants to start accepting card payments. But the bigger issue for the sector is over the supported technology - currently the mobile POS solutions are favouring a "signature" with the user running their finger on the smart phone screen.

However, since 2004 Chip and PIN has been compulsory in the UK and Ireland and as yet, while the plug-in card readers can read the card chip, they do not support the secure PIN verification. iZettle have recently got into trouble with Visa as a result of their authentication and so a more long winded approach has been devised, which is less user friendly and will thus undoubtedly slow the practical adoption.

Anyway - this technical hurdle is surely only a blip. We're sure there will be many further advances in mobile POS to come and expect we'll be involved ourselves in some way. More details on that in the future.

Read the full artcile at TechCrunch: Make Way For Another European Square: SumUp Launches With $20M+ In Backing